Fink’s data-center inflation warning is real—but the near-term pressure runs both ways
Larry Fink’s warning captures a genuine AI supply constraint, but faster construction is not automatically disinflationary. More computing capacity can eventually reduce scarcity and support productivity; the buildout can first intensify competition for electricity, equipment, labour and capital.
Overview
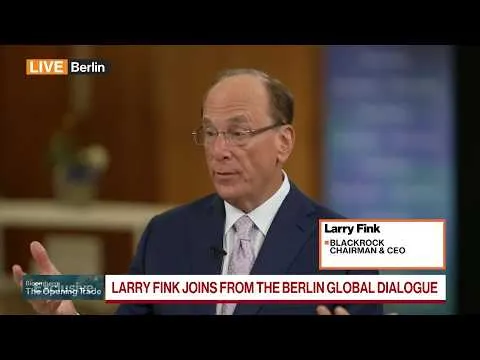
BlackRock Chairman and CEO Larry Fink is directionally right that constrained computing capacity can keep AI-service costs high and delay productivity gains. The broader inflation conclusion is conditional, however. Accelerating data centres may lower compute prices over time, while initially raising demand for power, grid equipment, construction and financing. The economic result depends less on the number of facilities alone than on whether energy supply, networks and cost-allocation rules expand with them.
Facts
- In an interview released on October 21, 2026, Fink said more data centres and computing capacity could bring down compute costs. (finance.yahoo.com)
- BlackRock identifies Fink as its chairman and chief executive officer. (blackrock.com)
- The Berlin Global Dialogue scheduled Fink for an October 21 session moderated by Bloomberg’s Francine Lacqua. (berlinglobaldialogue.org)
- The International Energy Agency forecasts global data-centre electricity consumption rising from 485 terawatt-hours in 2025 to 950 TWh in 2030. (iea.org)
- The IEA estimates the largest data-centre operators will spend more than $700 billion in capital expenditure during 2026, mostly on new facilities. (iea.org)
Main narrative
Fink’s argument starts with a straightforward scarcity mechanism. Demand for artificial-intelligence computing is rising faster than the facilities, chips and electricity systems needed to supply it. If capacity remains scarce, cloud providers can charge more for access, companies may limit AI use, and the diffusion of productivity-enhancing tools can slow. “The faster we can build out more data centers,” Fink told Bloomberg, “the faster we could bring down the cost.” (finance.yahoo.com)
That mechanism is credible, but it describes the prospective benefit of additional supply rather than the entire inflation path required to create it. Data centres are capital-intensive facilities competing for transformers, turbines, semiconductors, construction workers, land and electricity. Federal Reserve Governor Lisa Cook said in September that AI investment could create wider price pressure because data-centre construction uses inputs shared with other sectors. She also argued that eventual productivity gains could provide modest disinflation, although their timing and magnitude remain uncertain. (federalreserve.gov)
The distinction is between a relative price and economy-wide inflation. Scarce computing capacity can make AI services more expensive without necessarily producing a persistent increase across the overall price level. The risk becomes broader when data-centre demand raises electricity, equipment, financing or labour costs paid by households and unrelated industries. Federal Reserve meeting minutes from June similarly recorded expectations that AI investment would maintain pressure on technology and electricity prices, alongside the possibility that later productivity gains would reduce production costs. (federalreserve.gov)
The IEA’s latest evidence shows why neither outcome is automatic. A data centre requiring new generation or network investment can raise bills for existing customers if those costs are spread across the rate base. A facility using spare capacity and paying its full share can instead improve utilisation and lower pressure on bills. Large-load tariffs, minimum-payment commitments and exit fees therefore matter as much as construction speed: they determine whether infrastructure risk sits with developers or other electricity users. (iea.org)
Fink’s position also comes from an institution with direct exposure to the investment opportunity. BlackRock and its partners established an AI Infrastructure Partnership seeking to mobilise $30 billion in equity and as much as $100 billion including debt for data centres and supporting energy infrastructure. That commercial interest does not invalidate his diagnosis, but it reinforces the need to distinguish the societal case for abundant computing from the investment case for building more assets. (blackrock.com)
The bounded conclusion is that slow construction can preserve costly compute scarcity and postpone AI-related productivity. Faster construction can ease that constraint, but only becomes disinflationary if electricity generation, grids and equipment expand sufficiently and developers bear the costs they create. Otherwise, lower future compute prices may arrive after a period of higher power, construction and financing costs.
Context / evidence
The strongest evidence for Fink’s concern is the collision between rapidly increasing computing demand and slower physical infrastructure. The IEA says planning systems, chip manufacturing and energy supply chains are constraining expansion, while AI-focused data-centre electricity consumption is projected to triple between 2025 and 2030. (iea.org) Yet the agency also finds that data centres can either raise other customers’ electricity bills or spread fixed network costs across greater consumption. The outcome depends on existing capacity and how regulators assign connection costs and project risks. (iea.org)
Impact
For AI users, constrained capacity can mean higher service prices or slower access to advanced models. For households and ordinary businesses, the more immediate issue is whether utility regulators allow grid and generation costs to flow into general electricity rates. The IEA forecasts data centres will drive around half of the increase in US electricity demand through 2030, making tariff design and network planning material economic decisions rather than narrow technology policy. (iea.org) Investors face a different trade-off: delayed connections can weaken project returns, while excessive building based on speculative demand can leave underused infrastructure and unpaid network costs. (iea.org)
Outlook
The thesis can be tested through four indicators: compute-service prices, data-centre connection times, electricity tariffs in high-growth regions and productivity outside the technology sector. Falling compute prices alongside stable utility bills would support Fink’s supply argument. Rising power bills or construction costs without wider productivity growth would indicate that infrastructure expansion is shifting, rather than eliminating, inflation pressure. The IEA’s 2030 projection of 950 TWh provides a demand benchmark, but actual growth, credible grid-connection queues and the financing terms attached to new projects will be more useful near-term signals. (iea.org)