JPMorgan’s 7% 60/40 forecast restores the case for balance—but not simplicity
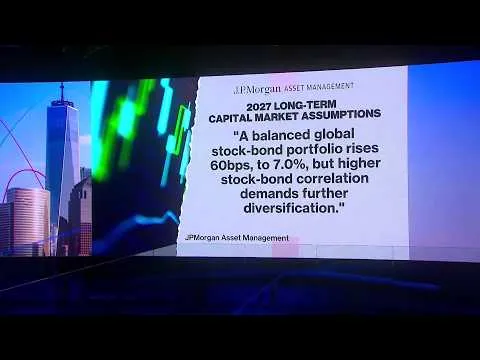
J.P. Morgan’s improved return assumptions strengthen the strategic case for balanced portfolios, but its own risk analysis argues against treating the traditional stock-bond mix as sufficient diversification.
Overview
J.P. Morgan’s 7.0% annualized forecast restores the long-term economic rationale for a global 60/40 portfolio after years in which low bond yields weakened its expected return. The more consequential judgment, however, is that balance no longer means relying on stocks and bonds alone. The firm expects higher stock-bond correlations and uneven inflation to make broader diversification more valuable, although its proposed alternative-heavy solution carries costs and risks that the headline return does not capture. (am.jpmorgan.com)
Facts
- J.P. Morgan Asset Management released its 2027 Long-Term Capital Market Assumptions on October 19, 2026; the estimates use a 10-to-15-year investment horizon. (am.jpmorgan.com)
- The projected compound annual return for a USD global 60/40 portfolio is 7.0%, up 60 basis points from the 6.4% assumption in the 2026 edition. (am.jpmorgan.com)
- The model portfolio comprises 60% MSCI ACWI equities and 40% Bloomberg US Aggregate bonds, with quarterly rebalancing. (am.jpmorgan.com)
- J.P. Morgan forecasts 7.5% annual returns for both U.S. large-cap and global equities, 5.3% for global aggregate bonds and 6.7% for diversified hedge funds. (am.jpmorgan.com)
- A modeled portfolio with 30% in diversified alternatives has a 7.5% projected return and a Sharpe ratio 21% above the simple 60/40 portfolio. (am.jpmorgan.com)
Main narrative
The headline improvement is straightforward: J.P. Morgan has raised the expected annual return for a USD global 60/40 portfolio from 6.4% to 7.0%. The forecast does not describe what investors earned in 2026 or promise what they will earn next year. It is a compound annual assumption for the next 10 to 15 years, built from expected yields, valuations, earnings, growth, inflation and currency movements. (am.jpmorgan.com)
The mechanism behind the upgrade matters more than the round number. Higher starting yields have restored bonds as a source of income rather than merely an expensive hedge. J.P. Morgan projects global aggregate bonds returning 5.3%, while its U.S. large-cap equity forecast rises by 80 basis points to 7.5%. That combination pushes the modeled stock-bond frontier upward and improves the prospective reward from holding both asset classes. (am.jpmorgan.com)
Yet the report does not signal a return to the comparatively simple portfolio logic associated with the disinflationary decades before the pandemic. It expects inflation to average a manageable level over the full horizon while remaining volatile because of government deficits, economic nationalism and intermittent supply-demand imbalances. Those conditions can cause stocks and bonds to decline together, reducing the protection that the bond allocation is expected to provide during equity stress. (am.jpmorgan.com)
J.P. Morgan’s answer is a broader portfolio rather than abandonment of 60/40. Its modeled allocation with 30% in diversified alternatives raises the projected annual return to 7.5% and improves the Sharpe ratio by 21%. Real assets are intended to add inflation resilience, while hedge funds and private-market strategies are expected to capture returns less dependent on broad public markets. The firm raised its diversified hedge-fund assumption by 140 basis points to 6.7%, partly because higher interest rates can increase returns earned on collateral and short positions. (am.jpmorgan.com)
That result should be read as an allocation hypothesis, not a free return enhancement. Private assets can restrict access to capital, reported valuations may adjust more slowly than public prices, and realized performance can depend heavily on manager selection. J.P. Morgan itself notes that alternatives bring implementation considerations and that its assumptions are illustrative rather than guarantees. (am.jpmorgan.com)
The forecast’s most important proposition is therefore conditional. A balanced portfolio again has a credible income base, but its resilience depends on whether investors diversify across distinct economic exposures rather than merely adding more holdings. The projected advantage of “60/40+” will be meaningful only if alternatives deliver differentiated net returns when public stocks and bonds are under simultaneous pressure.
Context / evidence
The assumptions were estimated as of September 30, 2026, through a process involving more than 90 researchers, economists and portfolio managers and covering more than 200 assets in over 20 base currencies. The alternative allocation behind the 7.5% projection is specifically defined: 40% global equities, 30% U.S. aggregate bonds and 30% divided among private equity, real estate, real assets, private credit and hedge funds. It is therefore not a generic comparison between public and private markets. (am.jpmorgan.com)
Counterpoint / knowledge gaps
The strongest counterargument is that the conventional 60/40 portfolio may already provide adequate diversification: bonds again offer meaningful income, and adding alternatives can introduce illiquidity, leverage, higher fees, valuation uncertainty and manager-selection risk. J.P. Morgan’s comparison is model-based rather than evidence that investors will receive the projected uplift. The report does not establish how a liquid, low-cost public-market portfolio would compare after alternative-asset fees, access constraints and implementation differences. Actual stock-bond correlations, realized AI productivity and inflation volatility would help distinguish the two cases.
Impact
For asset allocators, the forecast raises the strategic return benchmark for a simple balanced portfolio by 0.6 percentage points a year relative to J.P. Morgan’s previous assumptions. Institutions using long-term return estimates for contribution policies, spending rates or liability planning may therefore find the public-market starting point more supportive. The proposed additional 0.5-point return from alternatives is less directly transferable: investors must assess whether access, fees, liquidity limits and governance capacity permit them to reproduce the modeled allocation rather than treating 7.5% as universally attainable. (am.jpmorgan.com)
Outlook
Three observable tests will determine whether the constructive assumptions hold. First, wider AI adoption must produce economy-wide productivity gains rather than remaining concentrated among technology suppliers. Second, bond yields must provide income without being overwhelmed by renewed inflation or fiscal risk. Third, alternatives must deliver sufficiently low correlations and net returns to compensate for their fees and illiquidity. If those conditions hold, diversified balanced portfolios could approach the modeled 7.5% return. If productivity disappoints or inflation keeps stocks and bonds falling together, the forecast frontier would shift lower.